By: Our Staff Reporter
Ethiopia Today (Addis Ababa) East African governments are facing an urgent call to overhaul their telecommunications regulations as offshore satellite internet providers, such as SpaceX’s Starlink, rapidly disrupt the region’s digital landscape.
A landmark report released at the 2026 Africa CEO Forum in Kigali warns that while satellite technology offers unprecedented connectivity, its direct-to-consumer model poses significant risks to local investments, tax revenues, and national digital sovereignty.
The Reality of the Digital Divide: Cost Over Coverage
The report, unveiled during the summit at the Kigali Convention Centre, shifts the narrative on Africa’s digital divide. The primary hurdle is no longer a lack of infrastructure, but rather financial accessibility.
Currently, 86% of people in sub-Saharan Africa live within network coverage areas, yet only 38% to 43% are actually connected. This data reveals that the digital divide is fundamentally driven by high costs rather than a lack of physical towers.
For East African nations like Kenya, Rwanda, Tanzania, and Ethiopia, the challenge lies in balancing the immediate benefits of satellite services with existing mobile and fiber-optic networks. While satellite internet has rapidly gained traction in Kenya and Rwanda, markets like Tanzania and Ethiopia still grapple with massive affordability gaps, making hybrid connectivity models highly attractive.
The Risks of a Satellite Monopoly
While satellite internet is a vital tool for connecting remote schools, clinics, and rural communities, the report highlights a critical economic threat: offshore operators are skimming high-value urban and enterprise clients.
Traditionally, profits from these lucrative urban markets subsidize network expansion into rural areas. By losing these clients, local telecom operators face squeezed margins, which could discourage long-term private investment in terrestrial fiber-optics and cell towers.
Drastically reduce licensing and tax revenues flowing into government treasuries.
To counter this, the report urges East African states to implement strict regulatory parity, forcing satellite operators to comply with the exact same licensing, taxation, data handling, and national security rules as local terrestrial providers.
MTN Advocates for “Shared Infrastructure” to Fuel Growth
The call for regulatory overhauls aligns seamlessly with demands from Africa’s largest telecom operators.
Speaking at the forum under the theme “Scale or Fail: Why Africa Must Embrace Shared Ownership,” pan-African telecom giant MTN argued that the continent’s next phase of digital growth relies on cross-border cooperation.
“Africa’s next phase of growth will not be achieved through fragmented markets and duplicated infrastructure,” warned Nompilo Morafo, MTN Group Chief Sustainability and Corporate Affairs Officer. “It will be built through shared systems, coordinated investment, and trusted partnerships.”
MTN, which operates in 17 markets with over 290 million subscribers, lobbied for a unified approach built on three pillars: shared infrastructure to lower consumer costs,Policy harmonization to enable cross-border interoperability, and Co-investment models to share deployment risks.
Navigating the AfCFTA Digital Era
This tech showdown arrives at a pivotal moment as the African Continental Free Trade Area (AfCFTA) Protocol on Digital Trade enters its implementation phase. The protocol mandates signatory countries to establish interoperable infrastructure and seamless cross-border data frameworks—objectives currently hindered by fragmented national licensing regimes.
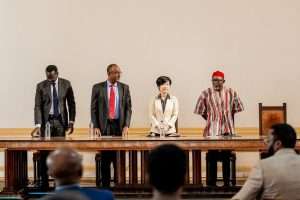
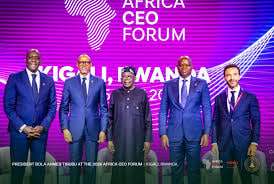
Host President Paul Kagame opened the forum by urging African leaders and the over 2,800 business executives in attendance to take greater responsibility for safeguarding the continent’s strategic interests.
The consensus from the summit is clear: East Africa must pivot toward a hybrid connectivity model. Rather than allowing offshore satellite networks to replace local infrastructure, governments must leverage satellite technology to complement domestic fiber grids, while aggressively investing in African-owned data centers, gateways, and network capacity.